How to Dispute and Sue TransUnion for Credit Report Errors

A Step-by-Step Breakdown of How to File, Support, and Escalate a Credit Report Dispute with TransUnion
A credit report is not just a collection of numbers; it is a reflection of your financial health and your overall financial journey. At its core, a credit report gives financial decision-makers a picture of your credit history and current credit situation, including your accounts, balances, payment history, and use of credit. It shapes how lenders evaluate your ability to borrow, how landlords assess your reliability as a tenant, and in some cases, how employers measure your stability and trustworthiness.
This concept is called your creditworthiness. A credit score is essentially a snapshot of that creditworthiness, placing you somewhere on the spectrum from "very bad" to "excellent." In other words, your TransUnion credit report carries weight far beyond the pages of a financial statement; it can open doors to opportunity or close them without notice.
So, it's obvious that when it comes to your credit report, precision is non-negotiable. There is no room for errors - accuracy is critical. Even a late payment that never happened, an account that doesn't belong to you, or incorrect identifying information can distort your report. Some errors can affect your credit score, while others can create identification or reporting problems even if the score itself does not change. Correcting those mistakes is essential if you want your report to represent your true financial standing.
While it is possible to start a TransUnion credit report dispute directly with the bureau, the process often proves to be more complex than it initially appears. For many consumers, it feels less like a straightforward correction and more like a brainteaser, full of delays, vague responses, and unexpected denials. The rules are there, but the path forward is not always obvious.
This is where experience matters. Consumer Attorneys stands ready to protect your rights and fight for accurate reporting. Our commitment: your story heard, your credit file accurate, your rights respected.
If you have ever wondered how to dispute TransUnion credit report errors effectively, the following guide offers a practical roadmap and highlights how the right assistance can make all the difference.
Ways to File a Dispute with TransUnion
You can dispute errors with TransUnion in three main ways: online, by mail, or by phone.
- Online disputes are generally the quickest way to get started. Use TransUnion's online dispute portal, review your report, identify the inaccurate items, and upload supporting documents where the portal allows. Some personal information changes require supporting documents by mail. Dispute investigations are generally completed within 30 days but can take up to 45 days in certain circumstances.
- Disputes by mail create a physical record, which can be critical if your case escalates. For many consumers, mailing a written dispute remains one of the most effective approaches. In a letter, you should include identifying details (name, birthdate, Social Security number, address), a clear description of what you're disputing, and copies (never originals) of supporting documents (statements, IDs, or court records). Importantly, don't sign waivers limiting your right to sue, even if a lawsuit feels unnecessary at this stage. Preserving this right is critical, because often it takes legal action to get errors corrected and lives back on track. To protect yourself, send your letter by certified mail and keep copies of all correspondence, mail receipts, and documents you send.
- Phone disputes are available as well at 800-916-8800. Phone disputes may be quick, but without a clear paper trail, they're harder to enforce. For that reason, most experts recommend online or mail disputes whenever possible. If you have phone conversations with anyone at TransUnion, keep detailed notes on the date, time, subject of the call, and the name of the representative you spoke with.
If you're not sure how to frame your letter or what supporting evidence will carry the most weight, Consumer Attorneys specializes in drafting persuasive dispute letters that combine clarity with legal authority and are difficult to dismiss.
Step-by-Step Guide to Disputing Your TransUnion Credit Report
Follow these steps to start a TransUnion credit report dispute:
Request your report - you can currently review your credit report from each of the three nationwide credit bureaus online for free once a week through AnnualCreditReport.com. Review it carefully for mistakes or suspicious entries. If you already have an account with TransUnion, you can also access your report directly through their portal at no cost. Struggling to find the right documents? Consumer Attorneys can obtain and analyze your report for you.
Identify the error - look for inaccurate accounts, incorrect late payments, or wrong personal details. Keep detailed notes about why each entry is inaccurate. Not sure what qualifies as an error? Our attorneys can review your report and confirm what should be challenged.
Gather documents.
Collect evidence such as bank statements, utility bills, government-issued IDs, or fraud reports. Strong documentation strengthens your case. Preparing the right paperwork can be tricky; our team ensures your dispute package is complete and compelling.
Submit your dispute - file your dispute with TransUnion online, by mail, or by phone, and always keep copies of your submissions. Not confident in your filing? Our dedicated team can handle the process from start to finish.
What TransUnion Gets Wrong Most Often
Not every dispute is about a single stray line item. Consumers who search for help with reporting wrong information, incorrect information, or who simply say "My TransUnion report is wrong," are usually describing one of a handful of recurring problems. Below are common types of inaccurate information consumers may encounter. Depending on how the error occurred and how TransUnion handled a dispute, these issues may implicate duties under the FCRA.
- Someone else's accounts, collections, or bankruptcy information in a mixed file. When TransUnion matches your identity to another consumer's data, often someone with a similar name, a shared address, or a family member, the result is a mixed file. A data furnisher may have reported accurately, but TransUnion's own matching process put the wrong tradeline on your report. A mixed file may support a claim under 15 U.S.C. § 1681e(b) if TransUnion failed to follow reasonable procedures to assure maximum possible accuracy.
- A paid or discharged debt still reported as owed. If you settled an account, paid it in full, or had it discharged in bankruptcy, but TransUnion continues to show a balance or an "open" status, that stale information can quietly suppress your score for years without you realizing why.
- Accounts belonging to a person with a similar name or a family member with the same name. This is a close cousin of the mixed file problem, and it's common enough among consumers with Jr., Sr., or common surnames that it deserves its own line. "TransUnion has my name wrong" is one of the most frequent complaints tied to exactly this scenario.
- Wrong name, address, employer, or Social Security number. Outdated or simply incorrect personal information doesn't always drag your score down on its own, but it's often the root cause of a mixed file or an account that isn't yours, and it should be corrected regardless of whether it's currently hurting you.
- Being reported as deceased. Consumers mistakenly listed as deceased can face credit denials and other serious problems because creditors accessing the report may treat the consumer as deceased.
- Records reported past the legal reporting window. Most negative information has to fall off your report after a set number of years under 15 U.S.C. § 1681c(a). When TransUnion continues to report an item past that window, the item should be removed outright, not merely "updated."
- An error that reappears after TransUnion already corrected it. Sometimes an item that was removed or corrected resurfaces on a later report, usually because a data furnisher re-reported it without being properly blocked. Under 15 U.S.C. § 1681i, if information was deleted after a reinvestigation, it generally may not be reinserted unless the furnisher certifies that it is complete and accurate. If it is reinserted, TransUnion must notify the consumer within five business days and maintain reasonable procedures designed to prevent deleted information from improperly reappearing.
Beyond these categories, we also regularly see identity theft, where fraudulent accounts or charges appear on a report the consumer never opened; these cases usually move faster once the consumer has on file: an Identity Theft Report from IdentityTheft.gov, proof of identity, and information identifying the fraudulent debts or accounts. Incorrect background checks can involve some of the same underlying data problems, though that process has its own rules. And the same categories of errors can also surface on rental screening reports, since many landlords pull TransUnion-based tenant data.
Consumer Attorneys is experienced in identifying which of these categories applies to your report and building the dispute or the case around it.
You've filed a dispute with TransUnion. Now what?
Once you've filed your dispute, it's important to track its progress:
- Online: Log in to the TransUnion portal to check the status of your dispute.
- By Mail or Phone: TransUnion sends the results after the investigation is complete.
- How long does a TransUnion dispute take?"By law, TransUnion generally has 30 days to conduct a reasonable reinvestigation, although the period can extend by up to 15 additional days in certain circumstances.
Important follow-ups to watch for:
TransUnion may send letters stating they were unable to identify you or that the dispute appeared to come from a third party, in which case no action was taken. If that happens, resend the dispute promptly and include copies of your ID, Social Security card, supporting documents, and a copy of the letter you received.
If you receive a dispute response but it's unclear, look for whether the item was marked "updated," "removed," or "verified." If the language is confusing, you can pull an updated copy of your credit report immediately, even before the 30-day period ends, to confirm what actually changed.
If no response arrives after the applicable reinvestigation period has expired, check the status and pull a fresh report. If nothing changes, having proof that your dispute was delivered, such as a certified mail record, becomes critical, since it may show that TransUnion failed to properly investigate.
If your dispute status with TransUnion hasn't changed or is marked as "completed" without corrections, our attorneys can escalate the matter and push for results. At that stage, a lawsuit may be the next step; see below for when you can sue TransUnion and what a case may be worth.
When You Can Sue TransUnion and What a Case Is Worth
Not every unresolved dispute turns into a lawsuit, but a meaningful number do. Before our attorneys evaluate a case, we generally look for one or more of the following:
- You filed a dispute and the error survived the investigation - TransUnion "verified" something that was never accurate.
- The same error came back on a later report after TransUnion had already corrected it.
- TransUnion never meaningfully investigated the dispute at all.
- The error caused a denial of credit, a lost apartment, a lost job offer, or another measurable harm.
If any of these describe your situation, you may have a claim under the Fair Credit Reporting Act (FCRA), the federal law that governs how TransUnion (TransUnion LLC) and other consumer reporting agencies are required to handle your information.
An unresolved dispute does not automatically mean you have a lawsuit. Whether you have an FCRA claim depends on the specific duty TransUnion violated and the harm that resulted. For a damages claim in federal court, the consumer must also have suffered a concrete injury.
The statutes that matter
A failure to follow reasonable procedures to assure accurate reporting is addressed under 15 U.S.C. § 1681e(b). A failure to properly reinvestigate a dispute falls under § 1681i. When TransUnion's conduct is shown to be willful, meaning it acted with knowing or reckless disregard for your rights, § 1681n applies. Even without proof of willfulness, negligent noncompliance under § 1681o still creates liability if TransUnion simply failed to exercise reasonable care in the first place.
What you can recover
For willful noncompliance, the FCRA allows recovery of actual damages or statutory damages of $100 to $1,000, plus punitive damages where allowed by the court. For negligent noncompliance, recovery is based on actual damages. The FCRA also includes a fee-shifting provision: if you win, TransUnion, not you, pays your attorney’s fees. That’s in addition to any damages awarded, and it’s a large part of why these cases can be pursued at no out-of-pocket cost to you.
Actual damages aren't limited to a lower credit score. They can include financial losses caused by inaccurate reporting, such as lost housing or employment opportunities, higher borrowing costs, documented out-of-pocket losses, and, where supported, emotional distress. Depending on the circumstances, documented time and expense spent addressing the problem may also be relevant. An adverse action notice can be important evidence connecting the inaccurate report to a denial.
What a case typically looks like
Some FCRA matters begin with pre-suit negotiations or a demand letter, while others proceed to litigation after the dispute process. Some cases resolve through settlement before trial, while others require discovery, motions, or trial. The timeline depends on the facts and procedural history of the case. As with our dispute work, there's no financial risk in bringing a case to us: we take FCRA cases on contingency, meaning no out-of-pocket cost to you. We only get paid if we recover on your behalf, and in a successful case those fees generally come from TransUnion, not from your recovery.
Class Action or Individual Lawsuit?
If you've searched for a TransUnion class action lawsuit, it helps to understand the difference before deciding how to proceed. A class action combines claims of consumers who share common legal or factual issues, and each class member's recovery depends on the judgment or settlement terms
An individual FCRA claim is different, as it focuses on the consumer's own facts and provable damages. The potential recovery depends on the circumstances of the particular case, so neither type of action automatically produces more compensation.
If TransUnion's conduct toward you looks like part of a broader pattern rather than a single reporting error, our overview of CFPB and FTC action against TransUnion under the FCRA covers that regulatory history in more depth.
Why Work with Consumer Attorneys
Trying to fix a TransUnion dispute or figure out whether you have grounds to sue on your own can be stressful and time-consuming. Disputes require persistence and a working knowledge of the FCRA; lawsuits require even more. Here's what you can expect when you work with us:
- Proven experience handling disputes and lawsuits against all major bureaus, including TransUnion, Equifax, and Experian, giving us insight into how each one operates and what strategies actually move a case forward.
- No out-of-pocket cost, ever. We take FCRA cases on contingency. You never pay upfront or during the process; our fees are recovered from TransUnion when we win, not from you.
- FCRA-based protection. If your rights under the Fair Credit Reporting Act have been violated, you may be entitled to corrections, compensation, or both. Our attorneys can determine whether your case qualifies.
Fight Back Today
Whatever stage you're at – whether you've just found an error or are ready to talk about a lawsuit – we're happy to walk through your options with you. Our goal is to make both the dispute process and the lawsuit process smoother, more effective, and firmly grounded in your legal rights. You don't have to take on TransUnion alone; get your free case reviewand find out what options may be available to you.
Take the Next Step
If you've found errors on your TransUnion credit report and feel unsure how to proceed, Consumer Attorneys can help assess the situation and explain whether we're able to assist.
As a nationwide practice with many years of experience, we understand the frustration of dealing with credit reporting errors. Our role is simple: to stand by your side, protect your rights, and guide you toward a fair resolution. We've seen every type of error and every kind of pushback, and we know how to make sure TransUnion does what the law requires.
We know the Fair Credit Reporting Act (FCRA), we know the credit reporting system inside and out, and we know how to secure the corrections and, when appropriate, the compensation you are entitled to.
- Call us today at (866) 938-3260 for a free case review
- Fill out our Contact Us form or start a live chat
- Email us anytime at info@consumerattorneys.com
Let's talk and take the first step toward fixing your credit report and restoring your peace of mind.
Frequently Asked Questions
Start through the official TransUnion online dispute portal. You can file online, by mail, or by phone. Written methods (online or mail) provide the strongest evidence.
Mail letters to TransUnion Consumer Solutions, P.O. Box 2000, Chester, PA 19016-2000.
Request your report, identify errors, gather supporting documents, and submit your dispute. For best results, work with Consumer Attorneys PLLC - legal professionals who know how to navigate the process and make sure your rights are fully protected.
It depends on the violation and the harm involved. For willful noncompliance, the FCRA allows actual damages or statutory damages of $100 to $1,000, plus punitive damages where allowed by the court. For negligent noncompliance, recovery is based on actual damages. In a successful action, the FCRA also permits recovery of costs and reasonable attorney's fees as determined by the court.
Small claims court has limits on the damages it can award and generally isn't equipped to handle federal FCRA claims, which typically belong in federal court. Most consumers with a viable FCRA case are better served working with an attorney who can pursue the full range of damages the law allows, at no out-of-pocket cost.
There is no fixed timeline. Some matters resolve through pre-suit negotiations or settlement, while litigated cases can take longer depending on discovery, motions, and the court. Strong documentation can make the facts easier to evaluate, but timing varies from case to case.
You're not legally required to have one, but FCRA cases can involve federal procedure, evidentiary standards, and negotiations with a bureau that has its own legal team..In a successful action, the FCRA permits an award of reasonable attorney's fees and costs. Consumer Attorneys handle accepted FCRA cases on contingency.
Possibly. Correcting an error later does not necessarily eliminate a claim for harm that occurred before the correction. If information that was deleted after a reinvestigation later reappears, the FCRA imposes specific certification and notice requirements. Whether that supports a claim depends on what TransUnion did, which FCRA duty was violated, and what harm resulted.
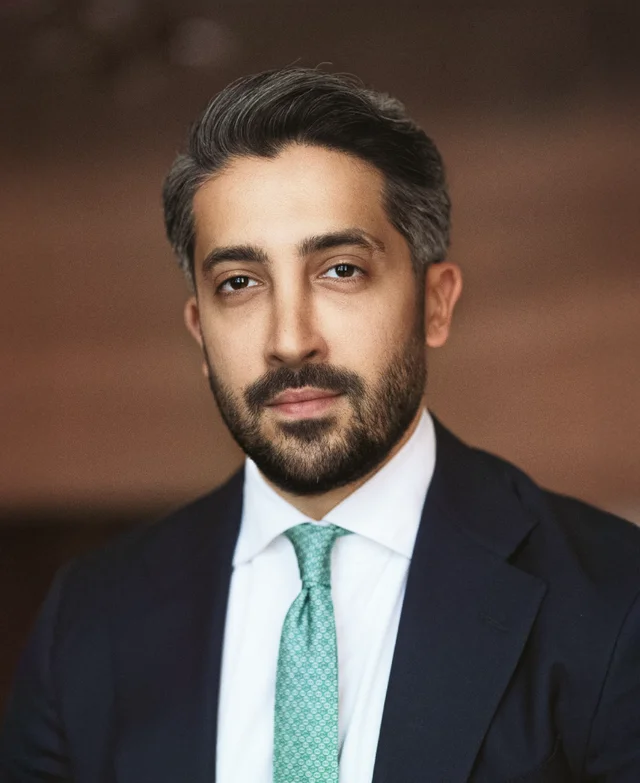
Daniel Cohen is the Founder of Consumer Attorneys. Daniel manages the firm’s branding, marketing, client intake and business development efforts. Since 2017, he is a member of the National Association of Consumer Advocates and the National Consumer Law Center. Mr. Cohen is a nationally-recognized practitioner of consumer protection law. He has a we... Read more
Related Articles
R
ONGS™